Telkom CEO’s 85 missing tax returns from 5 companies


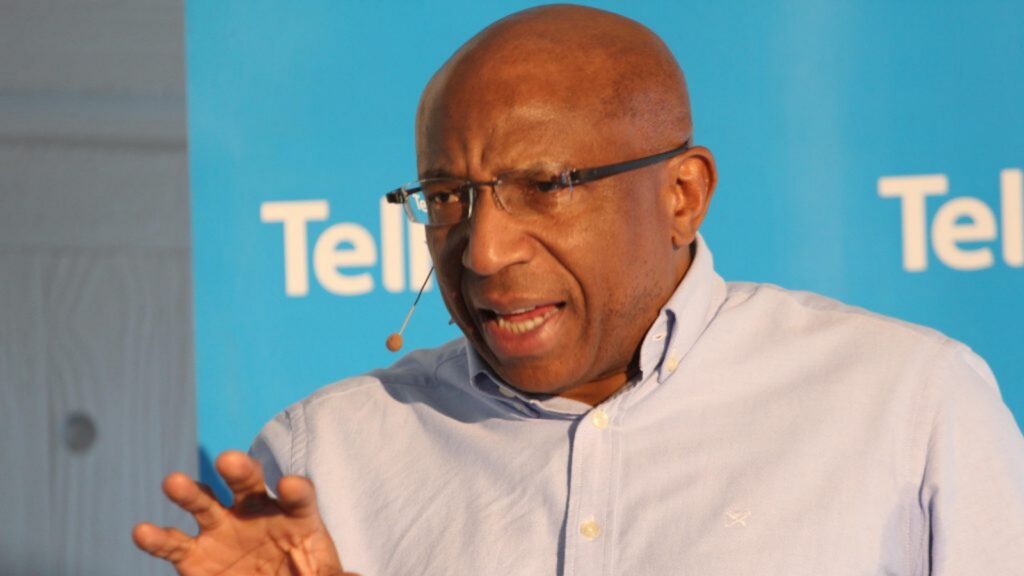
Former Telkom chief executive Sipho Maseko has been convicted after five companies under his directorship failed to submit 85 tax returns to SARS.
The conviction serves as a warning to South Africans that failing to meet company tax obligations can result in directors facing personal consequences.
This is according to Tax Consulting SA Partner and Head of Strategic Engagement & Compliance, Jashwin Baijoo, who said tax non-compliance can extend beyond the company to the individuals responsible for its affairs.
Maseko was convicted in the Palm Ridge Magistrates’ Court on 9 October 2026 in his representative capacity as a director of five companies.
These include One Fountain Properties, One Fountain Industries, One Fountain Capital, Afrifund Advisory Services and Afrifund Investments.
The charges relate to the failure to submit Pay As You Earn (PAYE), value-added tax (VAT), and corporate income tax returns over several years.
The case forms part of Project Honey Badger, an initiative involving the National Prosecuting Authority (NPA), the South African Revenue Service (SARS), and the Directorate for Priority Crime Investigation.
The aim of this project is to prosecute individuals and companies that fail to meet their tax obligations.
The NPA confirmed that an admission-of-guilt fine of R85,000 had been paid on behalf of the five entities. The companies have also submitted their outstanding returns, allowing SARS to assess them.
Baijoo explained that business owners often treat tax compliance as the responsibility of their finance departments or external tax practitioners.
However, directors and representatives responsible for a company’s financial affairs cannot assume that delegating these duties removes their accountability.
The Tax Administration Act 28 of 2011 (TAA) establishes obligations for taxpayers and provides for criminal offences for non-compliance.
Section 234(2)(d) addresses the wilful or negligent failure to submit a return or document required under a tax Act, where the applicable legal requirements are met. A conviction can result in a fine or imprisonment for up to two years.
This means that failing to submit a required return can create criminal exposure even where a business believes it owes no additional tax.
Filing obligations exist separately from the payment of tax. SARS needs the required information to determine a taxpayer’s position and assess whether revenue is due.
Baijoo said the Maseko case illustrates how outstanding returns can lead to criminal proceedings rather than remaining an administrative matter that a company can resolve at a later stage.
SARS can pursue individuals for company tax debt
Criminal liability for failing to submit returns is separate from the rules that allow SARS to hold individuals personally liable for a company’s tax debt, Baijoo explained.
Section 180 of the TAA provides for third-party liability where a person controls, or is regularly involved in, the management of a taxpayer’s overall financial affairs.
To impose this liability, SARS must determine that the person acted negligently or fraudulently in respect of the tax debt.
This can expose individuals to liability for the company’s outstanding tax, penalties and interest, Baijoo said.
The provision is particularly relevant to directors and others who exercise control over a company’s financial decisions.
However, personal liability is not automatic simply because someone holds a directorship or works for a company. The statutory requirements must be met.
Baijoo warned that directors and business owners should not assume that operating through a separate legal entity protects them from every consequence of tax non-compliance.
SARS has also strengthened its debt collection efforts, which is increasing the risks for businesses with outstanding tax obligations.
In cases where the legal requirements for personal liability are met, SARS may pursue the individuals concerned for company tax debt. This can create financial exposure beyond the original company’s balance sheet.
The risks of non-compliance

The consequences of failing to submit returns can also extend beyond the initial tax obligation, Baijoo said.
Criminal proceedings can affect an individual’s reputation, professional standing and commercial relationships. Depending on the offence, a conviction may also result in a criminal record and imprisonment.
He cautioned that unresolved tax issues can disrupt business operations and divert management attention from day-to-day activities.
SARS may also impose administrative penalties for outstanding returns, separately from any criminal proceedings or other lawful enforcement measures.
As such, directors should treat tax compliance as a governance responsibility rather than a task that can be left entirely to accountants or external practitioners.
Baijoo advised non-compliant taxpayers to identify and address outstanding obligations before SARS escalates enforcement.
Businesses should review their tax status, identify missing returns and verify that the underlying information is accurate. Returns should then be submitted through the appropriate SARS channels.
Companies with significant tax debts or potential exposure to personal liability should seek professional advice to assess their position and determine their options.
Where taxpayers intend to dispute an assessment or penalty, they should consider the applicable objection and appeal procedures.
Directors should also review the compliance status of related entities, particularly where they have control over or regular involvement in those companies’ financial affairs.
Where SARS has already issued a notice of personal liability, obtaining legal advice quickly is important to understanding the grounds for the notice and the available response.
Comments