Capitec shared details about ‘guerrilla warfare’ tactic


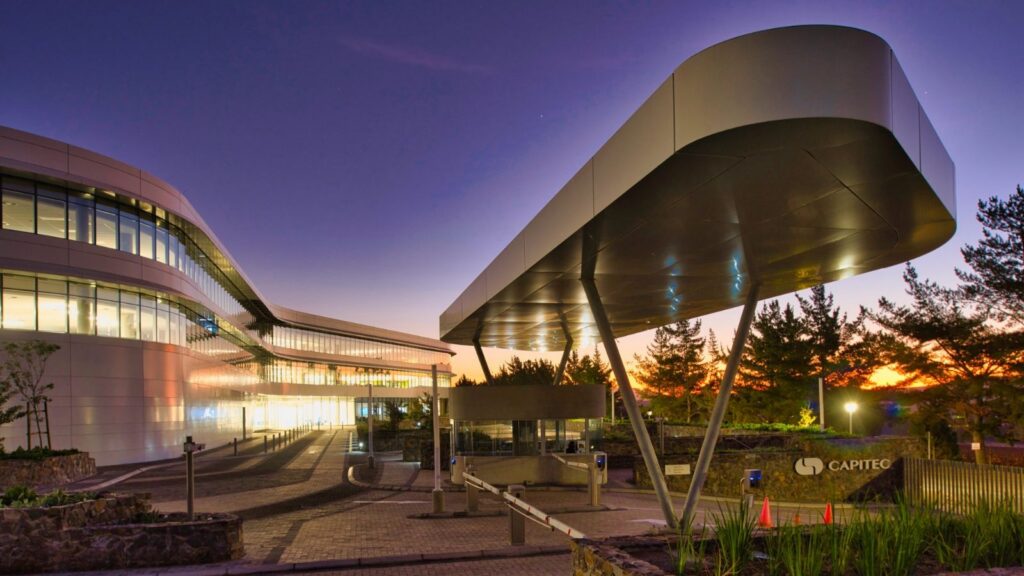
Former Capitec CEO Gerrie Fourie said the bank had to resort to “guerrilla warfare” tactics to win the market and take on the incumbents.
He explained that Capitec expanded from the outside in, targeting rural areas before it moved into cities where traditional banks were dominant.
Today, Capitec is the largest bank in South Africa by customer count, boasting 26.6 million active clients.
Fourie explained how Capitec reached this point and became a challenger to the traditional banks in an interview with Peregrine Capital.
When Capitec was founded in 2001, South Africa’s banking industry was dominated by a handful of large players, collectively known as the ‘Big Four’.
The Big Four consisted of Absa, Standard Bank, FNB, and Nedbank (formerly Nedcor).
Fourie explained that when Capitec launched, these incumbents misread it as a microlender, as the bank targeted lower-income and underserved markets.
This misreading allowed Capitec to establish its base beneath the Big Four’s radar, steadily building a strong customer base that the incumbents overlooked.
From the outset, Capitec’s aim has been to serve 95% to 96% of all South Africans, and it started by targeting the clients who had been ignored by traditional banks.
However, to attract these customers, Capitec had to resort to what Fourie described as “guerrilla warfare” tactics, where the bank’s representatives would go into these communities on foot.
Fourie recalled going to the Transkei in Capitec’s early days, spending three to four days to learn which banking products were already available.
He came back from this trip and told Capitec co-founder Riaan Stassen that there was only one offering available: Meeg Bank, which was minority-owned by Absa.
Fourie said Meeg had between five and eight branches in the Transkei at that time, which Capitec saw as a substantial opportunity.
“We immediately said, ‘Yeah, we need to do something’, and we opened 20 branches in Transkei,” he said.
“So, we came from the outside in: first rural areas and then city and urban areas. The vision was very clear. The strategy was how we had to manoeuvre to get to our objectives.”
Capitec’s growth
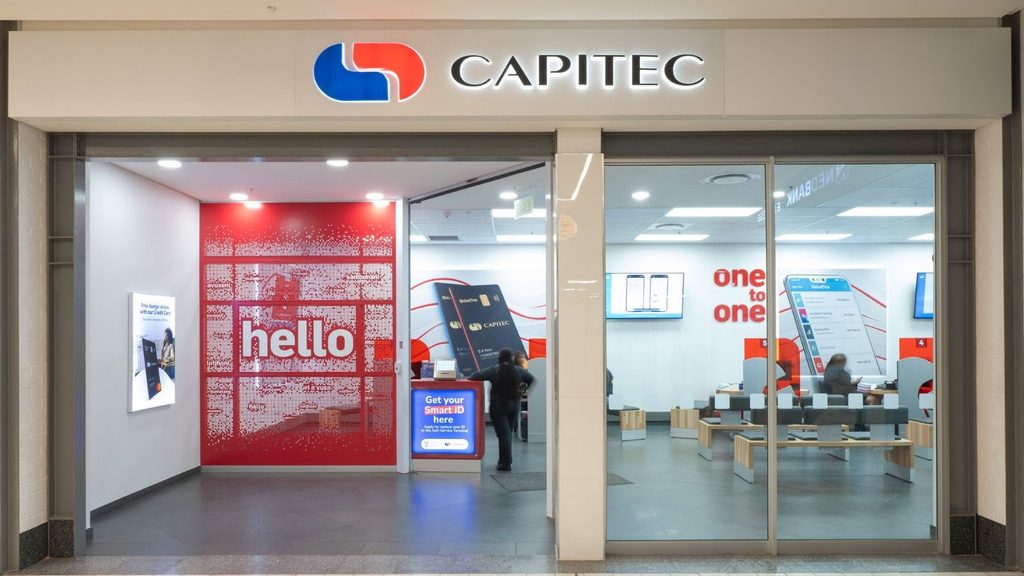
Fourie explained that since Capitec’s founders and early leaders spent years working in the liquor industry, they expected it to take years for the bank to gain momentum.
“When we started building the brand, we always said it would take us 12 years, because that’s how long it took whiskey and brandy and whatever to build a brand,” he said.
This projection rang true: It took between 11 and 12 years for people to really understand the Capitec brand.
In 2008, Capitec had grown to 2 million clients, which was still smaller than the bases of many incumbents. By 2013, it had 5.4 million clients.
Capitec had succeeded in locking down the rural, unbanked market and began stepping up its marketing aggressively in 2007.
The bank opened retail-style branches in busy shopping malls and introduced a simplified, low-fee structure that disrupted the Big Four’s setup. In 2009, it boasted 371 branches.
After the 2008 Global Financial Crisis, Capitec’s simplified approach resonated with even more customers, and its client base skyrocketed.
During this time, Capitec continued its “guerrilla warfare” tactics of going into the areas it wanted to expand into in person.
“There’s not a town in South Africa that I haven’t walked A to Z. I know where the taxi rank is, I know where Shoprite is and where Pick n Pay is,” he said. “I think I’ve opened up the first 650 branches.”
“We see our branches as critical for selling,” he said, explaining that physical branches have and always will play a crucial role in Capitec’s ecosystem.
“It’s because our 10,000 consultants are from the community, they sell into the community, and our branches are really now an extremely important selling tool.”
Today, Capitec has 885 branches across South Africa, the largest branch network of any retail bank in the country.
Login or register for unlimited free access.
Conversation
1 comments𝐀 𝐂𝐇𝐀𝐋𝐋𝐄𝐍𝐆𝐄𝐑 𝐁𝐀𝐍𝐊 𝐁𝐔𝐈𝐋𝐓 𝐎𝐍 𝐆𝐔𝐄𝐑𝐑𝐈𝐋𝐋𝐀 𝐖𝐀𝐑𝐅𝐀𝐑𝐄 — 𝐁𝐔𝐓 𝐖𝐇𝐄𝐑𝐄 𝐈𝐒 𝐓𝐇𝐄 𝐀𝐂𝐂𝐎𝐔𝐍𝐓𝐀𝐁𝐈𝐋𝐈𝐓𝐘?
Gerrie Fourie’s account of Capitec’s rise through “guerrilla warfare” tactics is an interesting reflection on how an institution can challenge established market players. However, there is a fundamental contradiction worth examining: what happens when the challenger itself becomes an incumbent, and begins to behave as though it is beyond scrutiny?
Capitec’s commercial success cannot be an exemption from accountability, transparency or institutional responsibility.
I formally brought a matter concerning SITUS, my financial technology proposition, to Capitec’s attention through a proposal addressed to its leadership, including Graham Lee, and two other staff in the bank’s product development and digital platforms, respectively. The subsequent emergence of Capitec’s cross-border transaction offering in collaboration with MamaMoney, following my proposal that was never answered but received, raised serious questions about the treatment of my intellectual property and the circumstances surrounding the development of comparably cloned functionality and architectural plan along with biometric login scopes on the application. These concerns were formally escalated through the National Financial Ombud Scheme on June 24, and to date there has been no response of any kind. Checking on the Ombuds system, shows case closed but resolution unreached. These are serious matters arising in financial integrity owed to me, staff, and the South African client-base as well as the whole demographic resonant of the MamaMoney remittance.
Let me say that again, ‘the matter has since been reflected as closed, with no response received from Capitec or the Ombuds.’
Let that sink in.
An institution that prides itself on understanding underserved communities, challenging established banking conventions and building trust with millions of customers should understand that accountability is not optional when it becomes the subject of a legitimate complaint.
Silence is not a resolution. Closure without substantive engagement is not an answer.
My complaint to Graham Lee and the subsequent Ombuds escalation were not made without warning. I explicitly communicated my intention to pursue further with international banking associations and investigative aides in financial institutions’ scrutiny should the matter remain unresolved. It has remained uncommunicated as far as I know, and am therefore left without option but to push higher in reporting a clear shenanigan racking millions off of an unconsented intellectual property.
The continued absence of a substantive response is particularly concerning when viewed against the applicable complaint-handling obligations, the Ombuds process and the constitutional principles of accountability, fairness and access to justice. Any applicable response deadlines and procedural obligations must be respected.
What Capitec may regard as institutional strength could or will ultimately become a self-consuming weakness: a pillar of commercial achievement undermined by an apparent culture of institutional arrogance.
I am therefore preparing to take this matter beyond domestic correspondence and pursue international cross-examination of the relevant circumstances, including the chronology of disclosures, the treatment of the SITUS proposal, the subsequent product developments and the institutional handling of the complaint.
This is not a request for preferential treatment. It is a demand for accountability.
A bank cannot continuously market trust while leaving legitimate questions about its own conduct unanswered.
Capitec’s growth story deserves recognition. Its accountability record deserves equally serious examination.
The world should be able to distinguish between a challenger that disrupts the banking industry and an incumbent that believes it no longer has to answer to anyone.
SITUS | GROOMEGA
Innovation deserves recognition. Institutional accountability deserves enforcement. Justice is always prevalent because it is always footed on uncompromised rule of law.