Dis-Chem CEO explains why he is more scared of Shoprite’s Checkers Sixty60 than Clicks


Dis-Chem CEO Rui Morais said the scale and growth of Shoprite’s Sixty60 offering poses a greater threat to his business than the traditional competitor, Clicks.
This is because Shoprite can leverage Sixty60’s popularity and reach to scale its Medirite offering, as the grocery retailer increasingly expands beyond its core competency.
In response to this growing threat, Dis-Chem is investing heavily in its digital estate, with R240 million spent in the first half of its 2027 financial year alone.
Morais made these comments at a strategic business update held at the X, bigly Labs offices in Melrose on Thursday, 29 October.
This update came after the release of Dis-Chem’s results for the six months through August 2026.
These interim results showed that Dis-Chem gained market share across all of its core retail categories.
Dis-Chem’s share of the personal care and beauty market expanded marginally from 17.4% to 17.8%, while its baby care share grew from 9.2% to 10.8%.
Crucially, in the healthcare and medical category, Dis-Chem’s market share increased substantially from 44.2% to 45.1%.
This makes Dis-Chem the biggest player in this market, which has become increasingly competitive over the past few years.
Previously, this market was dominated by two players: Dis-Chem and Clicks. These two have battled it out for market share for decades.
While independent pharmacies are also competitors in this sector, they account for a small share.
However, this market is undergoing a fundamental change, with ‘outside’ players such as Spar and Shoprite seeking greater market share.
Spar has operated in this sector for years. Its ‘Pharmacy at Spar’ brand launched in 2011 and is now available at 118 stores.
Shoprite has also been active in this sector for decades, but its Medirite brand has remained a small part of its business.
However, with the retailer’s Sixty60 offering continuing to take the market by storm, it now poses an imminent threat to the incumbents.
The Shoprite Sixty60 threat
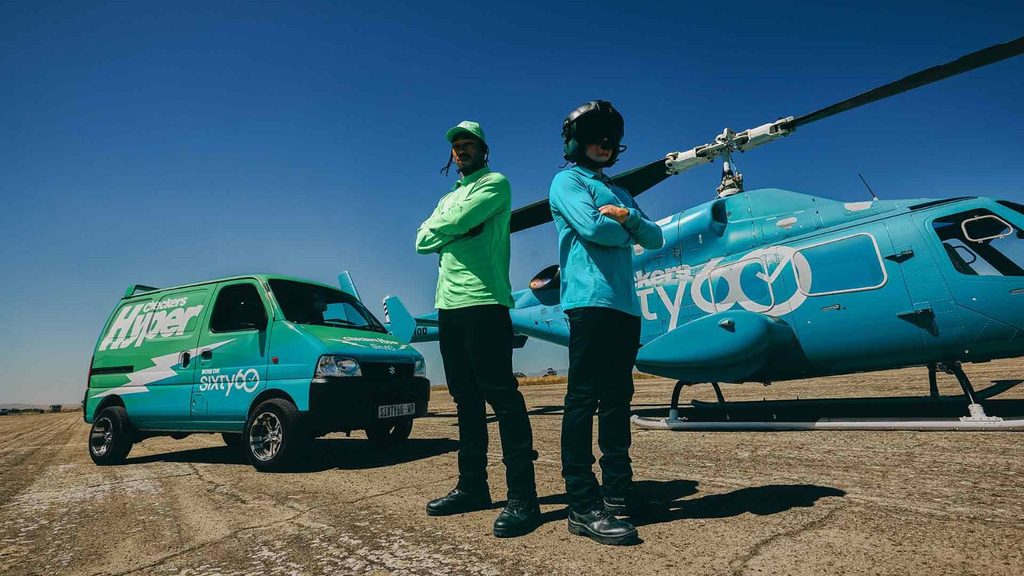
Morais explained that while Clicks was and remains Dis-Chem’s primary direct retail pharmacy competitor, he is now more concerned about the threat posed by Shoprite.
Shoprite has been a player in the medical services and supplies industry since 1999, operating under its Medirite brand.
Medirite runs dispensaries within Shoprite supermarkets and has a footprint of 140 in-store dispensaries.
In recent years, Shoprite has started rolling out stand-alone Medirite Plus pharmacies, offering a full-service healthcare destination.
Shoprite’s 2026 financial year results showed that sales at Medirite Plus retail pharmacies grew by 73.5%.
However, it is not this growth alone that concerns Morais. Instead, Shoprite’s Sixty60 offering is what poses the most potent risk.
Sixty60 is the largest e-commerce operation in South Africa and generates R25.5 billion in sales for its parent company.
It reported a record R6.6 billion in revenue in Shoprite’s 2026 financial year, now operating across 976 stores.
For reference, this is larger than Dis-Chem’s entire store footprint and comes close to Clicks’ 1,100 stores.
Morais explained that he is concerned about Shoprite’s ability to leverage its Sixty60 delivery infrastructure to scale fast in the pharmacy market and capture customer share.
“I see Clicks as a natural competitor, but I worry more about Shoprite, because they are able to use their Sixty60 asset to amplify their ability to scale,” he said.
This, he said, is a large part of the reason why Dis-Chem has been investing heavily in its digital estate.
Dis-Chem’s investments

Morais was referring to a multi-year effort by Dis-Chem to modernise its digital, physical, and operational assets to keep pace with shifts in omni-channel retailing.
He explained that this process was done in direct response to Sixty60’s growth, with Dis-Chem needing to be “at least as good as they are”.
Dis-Chem’s innovation unit, X, bigly labs, has been key in this process, tasked with re-architecting the retailer’s entire digital estate.
In the first half of its 2027 financial year, Dis-Chem deployed R240 million through X, bigly labs for this project. The investment was used to re-engineer Dis-Chem’s backend retail capabilities.
This included automated cataloguing, dynamic pricing, fulfilment, order management, and clinic and phamracy digitisation.
One of the biggest projects X, bigly labs has been working on over the past few months is building a new mobile app, which will be fully rolled out to the public in the fourth quarter.
This app is intended to replicate the physical store checkout experience, handling medical scheme claims, Apple Pay, and incorporating the Better Rewards loyalty programme.
At the same time, Dis-Chem has been rolling out its ‘Stores of the Future’, featuring a new format and design.
These stores feature centralised health hubs, experiential pods like body scanners and skin analysers, and integrated digitial touchpoints.
Dis-Chem reported that the two Stores of the Future it has rolled out so far have achieved initial trading densities 25% higher than early-stage traditional stores.
The group plans to roll out 16 more of these stores in the 2027 financial year, and is prioritising revamps of its existing base to suit the new format.
All of these innovations are coming at a cost for Dis-Chem. Its capital expenditure (capex) grew 54.8% to R712 million in the first half of the 2027 financial year.
This total comprises R492 million in expansion capex and R220 million in replacement capex, with another R489 million planned for the second half of FY2027.