South Africa’s government can get an extra R70 billion payday


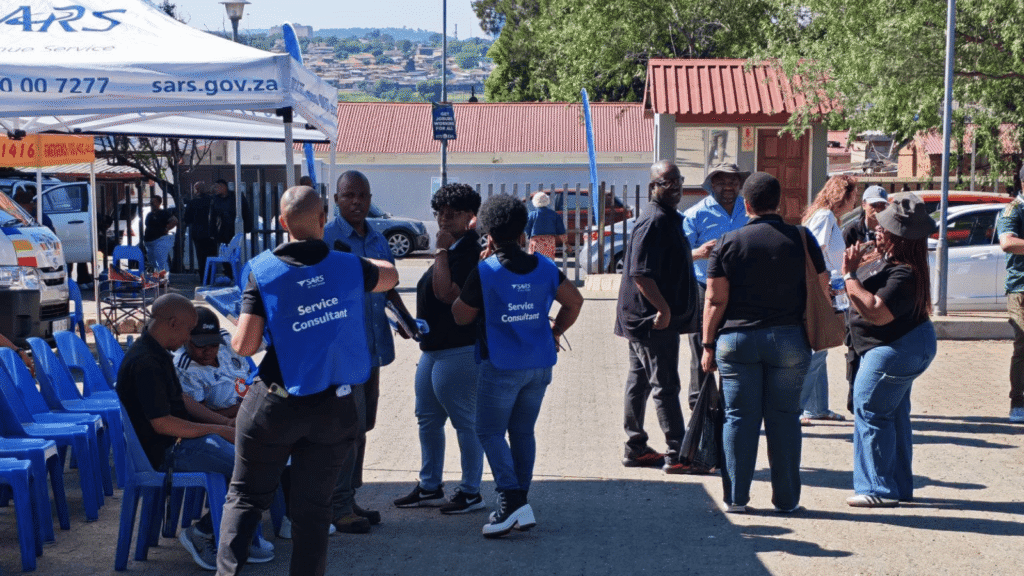
SARS could collect between R40 billion and R70 billion more in tax revenue than previously expected, as higher gold and platinum prices boost mining profits and other tax collections remain strong.
However, Investec economists warned that the additional revenue will only improve the country’s finances if the National Treasury uses it to reduce borrowing rather than allowing higher spending to absorb the gains.
The outlook will be a key consideration when Treasury presents its Medium-Term Budget Policy Statement (MTBPS) on 21 October 2026.
Speaking ahead of the statement, Investec Treasury Economist Tertia Jacobs said higher precious metals prices were likely to provide the main boost to tax revenue.
However, Jacobs cautioned that the benefit from mining revenue is cyclical and depends on production levels, operating costs and the exchange rate.
Higher gold and platinum prices are supporting mining profits and creating the prospect that tax collections will exceed the Treasury’s earlier forecasts.
Jacobs said she expects the additional revenue to reach at least R40 billion, although it could rise to between R60 billion and R70 billion.
However, she said the benefit may be smaller than the revenue boost South Africa experienced in 2021 and 2022, since higher prices alone do not determine how much tax mining companies pay.
Production volumes, operating costs and the rand exchange rate also influence mining profitability and the resulting tax collections.
Personal income tax and domestic value-added tax (VAT) collections have also performed well during the year.
At the same time, the country has seen improvements in the South African Revenue Service’s (SARS) tax-collection capacity, which has further strengthened the revenue base.
Jacobs said the tax authority is collecting R100 billion more annually through its efforts. Even so, South Africa still has a tax gap of R400 billion.
Improving compliance and closing this gap could provide a more sustainable source of additional revenue than relying solely on strong commodity prices.
Spending pressures
The main concern for Treasury is whether additional tax revenue will reduce government borrowing or be absorbed by spending pressures.
Investec Chief Economist Annabel Bishop explained that South Africa had already experienced a similar situation after the previous year’s revenue overrun.
“It’s concerning because when you see a revenue overrun like we saw last year, suddenly virtually all of that R19 billion to R20 billion was eaten up by additional expenditure that just flooded straight back in,” she said.
Bishop warned that unexpected spending, including costs associated with commissions of inquiry and additional contingency allocations, could again reduce the benefit of stronger revenue collections.
In particular, public-sector wages and salaries, particularly spending on administrative functions and higher-end salaries, are areas of concern.
As such, Treasury’s priority should be to control recurring expenditure while using any additional revenue to improve the country’s fiscal position.
Bishop said stronger revenue collections could help South Africa reduce borrowing costs and improve its prospects of credit rating upgrades, provided spending remains under control.
South Africa’s debt-to-GDP ratio remains high at 79%, which means that the cost of servicing government debt is a major pressure on the budget.
Higher borrowing costs have made this more difficult. South African government bond yields have moved towards 9%, increasing the cost of issuing debt.
Jacobs said the expected revenue overrun could improve both the main budget deficit and the primary budget surplus in the upcoming MTBPS.
The primary budget balance measures government revenue against expenditure excluding interest payments on debt. A sustained surplus would help the government manage its debt burden.
Treasury has already reduced the size of its bond auctions following stronger revenue collections, Jacobs explained.
She added that improvement in the debt-to-GDP ratio would support investor confidence, particularly if it proved sustainable rather than driven mainly by commodity prices.
The MTBPS is also expected to provide more details on the government’s proposed fiscal anchor. Bishop said the country’s framework should provide guidance on managing debt and deficits.
At the same time, it should allow flexibility during economic shocks. Sticking to rigid limits is difficult in a crisis, which requires extra borrowing.
A principle-based approach could instead establish a clear path towards fiscal sustainability while allowing temporary deviations when necessary.
Comments