Is your business bank account short-changing you? What an extra 1% means to your business.


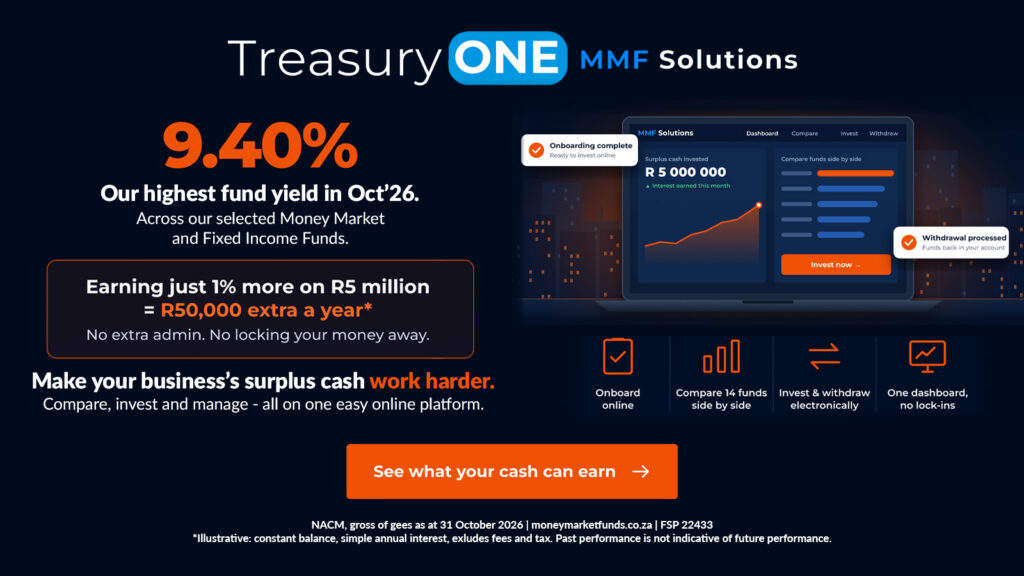
Your business worked hard for its cash. Here’s how to make sure that cash is working just as hard for you – safely, flexibly and without adding to your admin.
Most South African businesses keep a cash buffer: for payroll, VAT, provisional tax, supplier payments or the next big purchase.
Usually that money sits in a business current account or a call account, because it feels safe and it’s easy to get to.
But when did you last check what that account is actually paying you?
What 1% means for a business your size
Say your call account pays 6.5% a year and a money market fund is yielding 7.5%.
That’s a difference of one percentage point. Here’s what it adds up to over a year:
| Surplus cash | Extra interest at +1% | After 27% company tax |
|---|---|---|
| R500,000 | R5,000 | R3,650 |
| R1 million | R10,000 | R7,300 |
| R2 million | R20,000 | R14,600 |
| R5 million | R50,000 | R36,500 |
That’s money for nothing more than a better decision about where your cash sits.
You don’t sell more, cut costs or take on extra work.
And depending on what your bank currently pays, the gap could be bigger than 1%.
Illustrative only. Assumes a constant balance, simple annual interest and the 27% company tax rate; excludes fees. Money market fund yields change daily and past performance is not a guide to future returns.
“But is my money safe?”
It’s the right first question. Here’s how it works:
- Money market funds are regulated unit trusts. They’re collective investment schemes registered under CISCA and supervised by the Financial Sector Conduct Authority (FSCA).
- They invest in short-term, high-quality instruments such as bank deposits, treasury bills and other money market instruments, which keeps risk and price movement low.
- Your money is held in your company’s name with the fund.
“Can I get my money when I need it?”
Yes. There are no fixed terms or notice periods.
Withdrawals are typically paid out within [one to two business days], depending on the fund, so you can plan around payroll, VAT and other known payments.
Many businesses keep a few days’ operating cash in the bank and invest the rest of the buffer.
Compare, invest and manage in one place
Traditionally, getting a better rate meant phoning banks and asset managers, comparing terms and filling in separate paperwork for each.
For a small finance team – or an owner who is the finance team – that’s rarely worth the effort.
TreasuryONE’s MMF Solutions platform puts 14 money market and income funds from six leading South African asset managers side by side, showing yields, fees, liquidity terms and fund details.
Once you’ve chosen, you can:
- onboard online – most businesses are set up within 5 business days, with one set of FICA documents;
- invest electronically in one or more funds;
- track your balances and returns on a single dashboard;
- request withdrawals online when you need cash.
Real people behind the platform
The highest yield isn’t always the right choice.
If you need cash back within a day, or you’re investing your tax provision, liquidity and risk matter more than the last few basis points.
That’s why MMF Solutions is backed by TreasuryONE’s cash management specialists, drawing on more than 25 years of corporate treasury experience.
You can talk to a person before you invest.
Is your surplus cash working as hard as you are?
Your business has already earned the cash. A few minutes of comparison could make sure it’s earning what it should.
See what your balance could earn at www.moneymarketfunds.co.za or [email protected] to speak to a cash management specialist.
TreasuryONE (Pty) Ltd is an authorised financial services provider FSP no. 22433. Collective investment schemes are generally medium- to long-term investments; money market funds are not bank deposits, and the value of participatory interests may go down as well as up.